All Categories
Featured
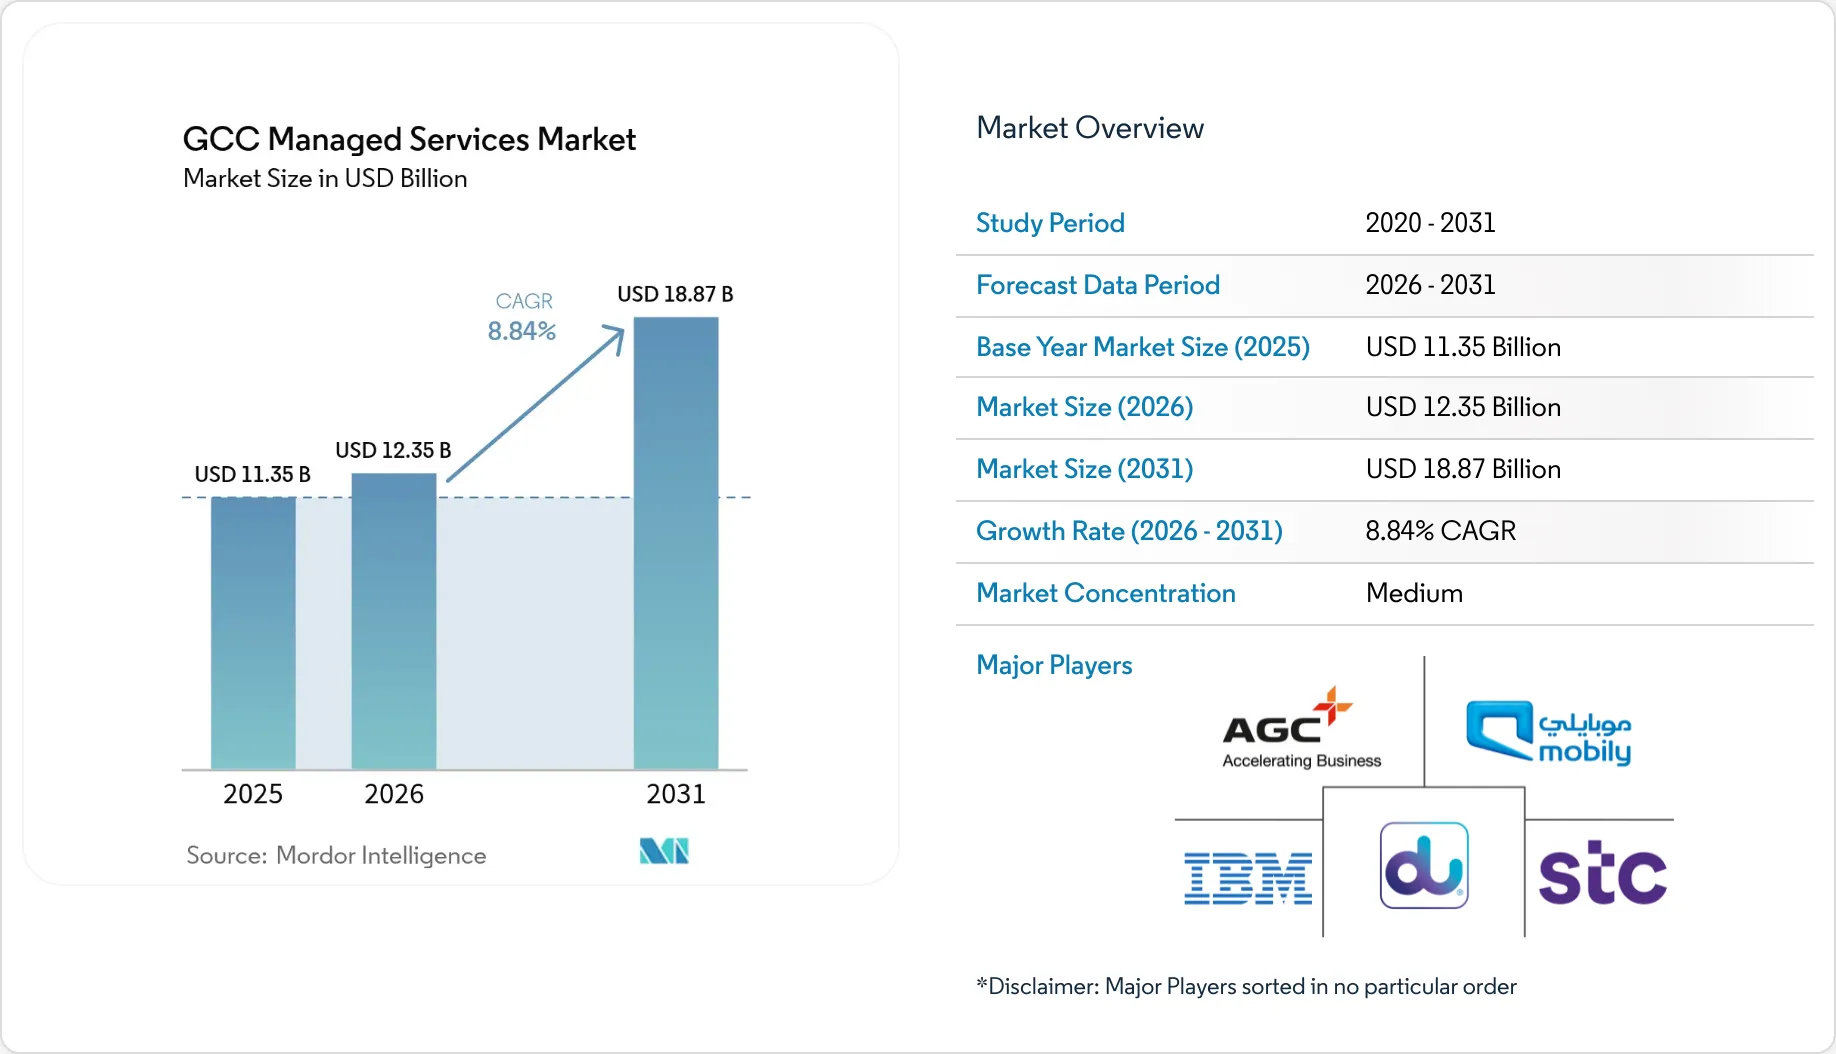
Rather than marking a cyclical rebound, 2026 is progressively seen as a consolidation year, in which diversification-led growth becomes more deeply ingrained in the area's financial model, lowering dependence on hydrocarbons and increasing strength to external shocks. Forecasts from significant institutions broadly assemble on a stronger GCC growth profile in 2026 than in 2025, supported by durable domestic demand, continued non-oil growth, and (to differing degrees) a firmer hydrocarbon contribution.
3.2 percent growth in 2025, speeding up to 4.5 percent in 2026. Sees momentum improving, with GCC output development forecasted to rise from 1.7 percent in 2024 to 3.3 percent on average in 2025, showing a shift toward more favorable total conditions.
Ways to Leverage GCC Research for SuccessThe IMF's World Economic Outlook (October 2025) tasks worldwide development alleviating to 3.1 percent in 2026, with advanced economies around 1.5 percent and emerging market and developing economies simply above 4 percent. On that contrast, a 4.44.5 percent GCC growth would put the area materially ahead of the world average and a little above (or broadly in line with) the emerging-market aggregate, strengthening the GCC's status as a relatively high-growth pocketprovided that regional threat conditions stay contained and reform momentum holds.
Information from the GCC Statistical Center show that non-oil sectors already represent more than 73 percent of total GDP, a share that has actually continued to increase as governments broaden financial investment in services, facilities, and innovation. According to Oxford Economics, non-energy activity across the GCC is predicted to grow by around 4.1 percent in 2026, supported by strong labor markets, improving credit conditions, and rising financial investment in innovation and AI-related facilities.
Can Market Research Define Dubai Corporate Growth?
Public-sector investment and reform stay main to sustaining this pattern. Policy steps focused on bring in foreign direct financial investment, alleviating foreign ownership rules, expanding capital markets, and supporting private-sector involvement continue to underpin non-oil growth and decrease the region's exposure to oil rate volatility. While hydrocarbons no longer control the growth outlook, oil revenues are expected to play an encouraging role in 2026.
Oxford Economics anticipates Brent crude costs to fall listed below USD 60 per barrel in early 2026, restricting the near-term contribution of oil extraction to GDP. Nevertheless, oil supply is anticipated to rise again in the 2nd half of the year, with a complete relaxing of remaining production caps likely by mid-2027.
Macroeconomic conditions throughout the GCC remain broadly helpful of development. Inflation is anticipated to remain low, with the IMF forecasting typical inflation of 2 percent across the area in 2026. Steady costs are assisting maintain real household incomes and underpin consumer costs, which Oxford Economics anticipates to grow by approximately 3.5 percent over 20262027.

Latest Posts
Long-Term Dubai Industrial Expansion Patterns in 2026
Essential Middle East Market Analysis Trends in 2026
Optimising Operational Efficiency through Advanced Business Research